Form 5472 and the US LLC Calendar: What UK Founders Take On Each Year

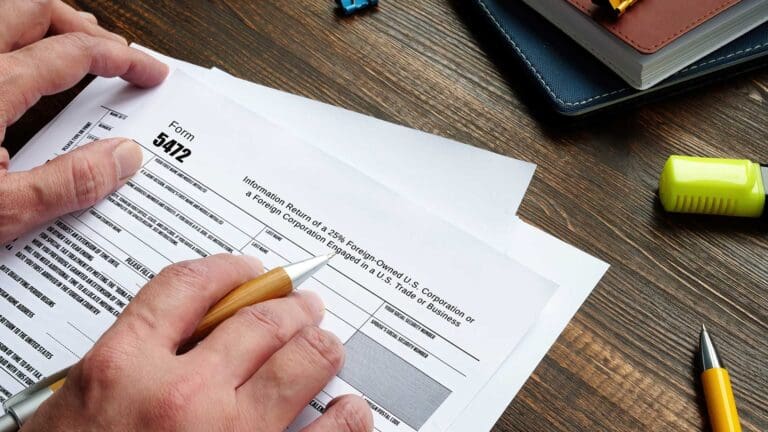
The item that matters most is Form 5472, an information return the IRS expects every year from a foreign-owned US company, even one that owes no US tax at all. Miss it and the stated penalty is 25,000 dollars. Almost everything else on the calendar is routine by comparison.
That imbalance is why so many British owners are caught out. Forming the company takes days and feels like the hard part. The obligation with real teeth arrives months later, sends no reminder, and sits in a set of IRS regulations most founders never read.
Why Form 5472 sits at the centre of the year
A US LLC with one owner is, by default, a disregarded entity for US federal tax purposes. It files no income tax return of its own, which is where the misunderstanding starts. Since the rules on foreign-owned disregarded entities were tightened, the IRS has required these companies to file a pro forma Form 1120 with Form 5472 attached, by the due date of that Form 1120, including extensions. For a company on the calendar year, that points to mid-April unless an extension is requested.
Form 5472 does not calculate tax. It reports transactions between the company and its owner: capital introduced, money withdrawn, loans in either direction, payments for services. The IRS instructions are blunt about the consequences. The 25,000 dollar penalty applies to a return that is not filed when due, and a substantially incomplete return counts as not filed. The same penalty covers a failure to keep the records the regulations require.
Nothing about this resembles the UK experience. Companies House sends reminders, and HMRC letters arrive with dates on them. A US LLC owned from Manchester or Leeds gets no equivalent prompt. The founder has to own the date.
A year on the calendar
Formation month. The articles are filed with the chosen state, a registered agent is appointed to receive legal and official mail there, and a US business address is arranged. Wyoming is a common choice for owners abroad because it levies no state income tax and does not require members’ names in its articles of organization.
The weeks after formation. The company needs an Employer Identification Number. The IRS online application is only open when the responsible party has a Social Security Number or an ITIN and the principal place of business is in the US. Owners outside the US apply by phone, fax or post using Form SS-4 instead, which takes considerably longer. Start this immediately, because banks and payment platforms ask for the EIN letter before anything else.
Throughout the year. Keep a ledger of every movement of money between you and the company. Each one is a potential Form 5472 entry, and reconstructing them in March from mixed accounts is where incomplete returns come from.
Spring. The pro forma Form 1120 and Form 5472 are due together. The IRS instructions give foreign-owned disregarded entities their own filing directions, including a dedicated mailing address, so check the current instructions each year rather than repeating last year’s routine.
Once a year, on the state’s schedule. The state annual report and the registered agent renewal both come round every year, on dates set by the state and the agent rather than by the IRS. They are modest, but a lapse can cost the company its good standing.
Whenever something changes. A new mailing address, a new business location or a new responsible party is reported to the IRS on Form 8822-B. A change of responsible party must be reported within 60 days.
What changes on the UK side, and what does not
Owning a US LLC does not move anyone’s tax residence. A UK resident remains a UK resident, and how HMRC treats the LLC’s profits, together with any relief for tax paid elsewhere, is a question for an adviser who works across both systems. The answer is not automatic, and it depends on the facts of the business. What a founder can do is keep the US and UK records reconcilable from the first transaction, so that whoever prepares either return is working from the same numbers.
It also helps to be clear about what the US company is for. It earns its place when the customers, platforms or payment rails a business depends on are American. It adds cost and administration without much benefit when the revenue is British or European.
Who keeps the calendar
Entrepreneurial time is finite, and none of these tasks grows the business. Founders who enjoy administration keep the calendar themselves and use a tax preparer for the annual return. Many split the work: a US business formation service handles the state filing, registered agent, business address and the EIN application for owners without a Social Security Number, and an accountant with cross-border experience signs off the federal return. CORPBOLT is one provider that works this way for owners based outside the US, leaving the tax judgement with the tax professional where it belongs.
Whichever route you choose, write the dates down on the day the company is formed. The founders who get into difficulty are rarely the ones who misunderstood the rules. They are the ones who assumed a quiet inbox meant nothing was due.
More Stories
Top 10 Link-Building Marketplaces Reviewed for 2026
Link-building marketplaces cut out many of these steps by giving buyers access to publishers in one place, along with information...
Alt-Net vs Big Telecom: Is switching really worth it?
Alongside the familiar national providers, a growing number of smaller network builders, often called alt-nets, are offering their own full...
Getting to know you: Filip Pesek, founder and CEO, DonnaPro
Filip Pesek is the founder and CEO of DonnaPro, a Slovenia-headquartered agency that places EU-based executive assistants with founders and...
German auto workers protest historic job cuts
The country’s carmakers are scaling back production amid high energy costs, US tariffs and Chinese competition Tens of thousands of...
Getting to know you: James Williams, co-founder and CEO, Sero
James Williams is co-founder and CEO of Sero, a Cardiff-based B Corp that upgrades social housing with insulation, solar panels,...
Getting to know you: Sarah Horrocks, founder, PALAIR
Sarah Horrocks is the founder of PALAIR, a London-based brand making premium padel and activewear for women and men, designed...