Wall Street Review: Small Caps Outperform as Bond Yields Ease

By Panos Mourdoukoutas
Small-cap stocks outperformed this week as investors rotated out of the volatile AI trade and into interest-rate-sensitive sectors, helped by a retreat in Treasury yields.
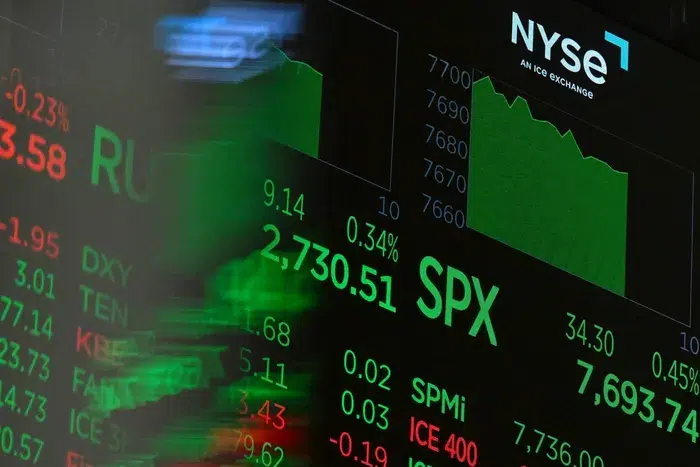
The Russell 2000 gained 2 percent for the week, leading the major U.S. equity indexes. The Dow Jones Industrial Average slipped 0.41 percent to close Friday at 52,215. The S&P 500 fell 0.47 percent to 7,623, its weekly low, while the Nasdaq Composite lost 0.71 percent, ending near its weekly low at 25,955.
The move reflected a broader shift in how investors allocate assets. Concerns about heavy capital spending and rising debt among data center builders weighed on high-flying AI-related shares, while demand for haven assets such as U.S. Treasuries helped push bond yields lower.
Worries over French sovereign debt also supported demand for U.S. government bonds, with French yields climbing to 5.11 percent.
Lower yields eased pressure on sectors more sensitive to borrowing costs, including small caps, homebuilders, and real estate investment trusts (REITs).
The yield on the U.S. 10-year Treasury note moved unevenly through the week but ended lower overall, despite a late-week rebound. It rose to 5.13 percent early in the week, pulled back toward 5 percent as investors bought Treasuries, and closed above 5 percent Friday as oil prices climbed.
Oil remained a key market mover. Brent crude rose above $116 a barrel on Friday, a four-year high, amid concerns that the United States could resume strikes on Iran. For the week, oil prices rose about 6 percent.
AI Spending Concerns
The week’s trading underscores growing market tension over AI-related spending. Tech stocks opened the week on firmer footing, helped by bargain hunting after the prior week’s sell-off and a rebound in Korean equities, with the Kospi rising 1.70 percent. Marvell Technology, Nvidia, and Amazon led early gains.
But the tech rebound proved uneven. The Nasdaq rose 1.11 percent Monday and gained Wednesday again after strong earnings from Super Micro Computer and Space Exploration Technologies reignited enthusiasm for AI infrastructure spending. Those shares rose 9.55 percent and 7.79 percent, respectively, while Nvidia, AMD, and Palantir also advanced.
Tech momentum reversed Thursday sharply after Meta and Tesla earnings renewed questions about AI spending plans.
Meta shares fell after the company said it planned to allocate another $825 billion to AI-related capital expenditures, raising investor concerns about cash depletion and rising debt.
Tesla shares dropped after the company cut its capital spending plan from $25 billion to $20 billion, prompting worries that it may not be investing enough in AI to keep pace with competitors and execute its plan to merge with Space Exploration Technologies.
A warning from chip-equipment maker Lam Research about supply-chain constraints added to the selling pressure: semiconductor shares sold off heavily, with the Philadelphia Semiconductor Index falling 6.79 percent Thursday and helping drag the Nasdaq down 2.60 percent for the day.
Rotation
The broader market held up better as investors shifted money into defensive and rate-sensitive areas. Health care and pharmaceutical shares gained, with the Health Care Select Sector SPDR Fund rising 2.37 percent during Tuesday’s rebound. Solid earnings from 3M lifted sentiment outside technology, while a strong Procter & Gamble report supported the Dow later in the week.
The rotation was most visible in small caps. After selling off in earlier sessions, the Russell 2000 rebounded sharply on Tuesday, rising 1.65 percent as Treasury yields fell. It also held up better than the Nasdaq during the late-week tech sell-off.
“This looks more like rotation than a broad flight to safety. Among investors adapting, their portfolios, most plan to increase exposure to at least one asset, even as others reduce holdings,” U.S. investment analyst Bret Kenwell told The Epoch Times.
He said Generation Z investors adding crypto assets while cutting stocks “is the clearest example of that two-way repositioning, rather than a wholesale move into cash.”
Friday’s trading turned negative after bond yields followed oil prices higher.
American Express added to the pressure after announcing plans to cut 5 percent of its workforce. Dow and S&P 500 component shares fell 3.68 percent, pushing the Dow down 1.23 percent and the S&P 500 down 0.52 percent. The Nasdaq slipped 0.21 percent, while the Russell 2000 fell 0.29 percent.
Fed Meeting in Focus
Investors now turn to the Federal Reserve’s next policy meeting, with inflation pressures from higher oil prices complicating the outlook for interest rates.
Arthur Azizov, CEO and founder of B2BROKER Group and B2BINPAY, said the central bank faces a difficult trade-off because higher borrowing costs would do little to address oil-driven inflation while adding pressure to a weakening labor market.
“The Fed will almost certainly keep rates unchanged at the next meeting, and the market already believes that there will be another hike in December, but I am much less convinced, because the Fed is caught between two risks,” Azizov told The Epoch Times.
“The September rise was driven by expensive oil, which pushed inflation up, but no interest rate decision can bring more oil into the economy.”
Kenwell said recent volatility also reflects uncertainty ahead of the midterm elections.
“History suggests that pre-election volatility does not necessarily derail the broader market. Midterm years have typically been the weakest and most volatile part of the presidential cycle,” he said.
“But the S&P 500 has averaged an 18.5% gain on a total return basis in the 12 months following midterm elections and has finished higher in every cycle over the past 75 years.”
More Stories
Judge Rejects Bail for Former OpenAI Employee Accused of Installing Listening Device
By Lear Zhou SAN FRANCISCO—A federal judge rejected a bail request of a former OpenAI engineer who was accused of...
Trump Announces $4.2 Billion Audi Auto Manufacturing Investment in Georgia
By Travis Gillmore PERRY, Ga.– President Donald Trump unveiled a $4.2 billion investment from automaker Audi to develop its first...
DOJ Gives California County Election Officials 48 Hours to Help Verify Voters’ Citizenship
By Tom Gantert The U.S. Department of Justice has sent letters to county election officials in California warning them they...
French Officials Say 1,300 Arrests Made Amid Latest Unrest
By Jack Phillips More than 1,300 people were arrested in another day of protests and riots, after a mass march...
RFK Jr. Announces American-Made Seafood Label at Midterm Rally in Florida
By Troy Myers Health and Human Services (HHS) Secretary Robert F. Kennedy Jr. has announced a new American-made label for...
France on Fire: Who Is Behind the Riots, Who Benefits From the Chaos—and Could a Fallen Republic Put Nuclear Weapons at Risk?
By Stephen Zogopoulos, Founder & Chief Executive Officer, USNN World News France Is Not Simply Protesting. The Republic Is Facing...