Wall Street Review: Nasdaq Sinks 4.48 Percent as Inflation Fears Hit AI Stocks

By Panos Mourdoukoutas
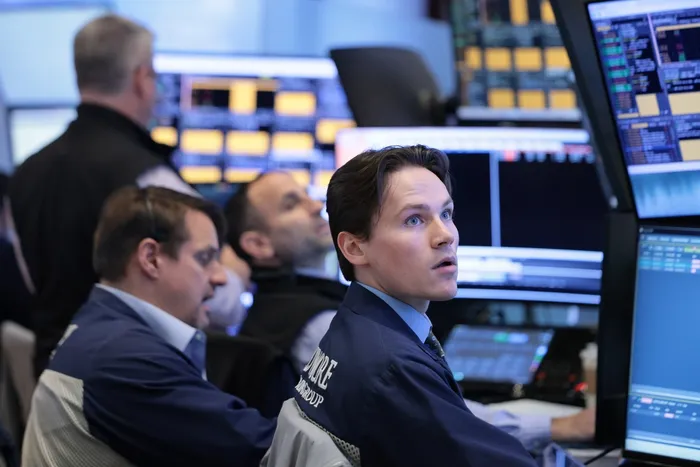
The Nasdaq Composite fell 4.48 percent for the week as hotter-than-expected inflation data sent Treasury yields higher and investors reassessed whether heavily indebted artificial-intelligence companies can generate returns sufficient to justify their enormous investments.
The tech-heavy index dropped 2.14 percent on Friday alone, with AI infrastructure companies among the biggest losers.
CoreWeave fell 13.65 percent on the day and 25.21 percent for the week, while Nebius Group lost 12.18 percent on Friday and 25.15 percent for the week. Palantir Technologies, another popular AI stock, fell 7.22 percent on Friday despite strong financial performance.
The sell-off reflected growing tension in financial markets: AI-related companies have earned considerable investment on expectations of rapid growth, but higher borrowing costs and questions about the profitability of AI infrastructure projects threaten to undermine the investment narrative.
Inflation added to those concerns. The consumer price index (CPI) rose 3.7 percent annually in September, up from 3.4 percent in each of the previous two months and above economists’ expectation of 3.6 percent.
The producer price index (PPI) then showed wholesale prices rising 6.3 percent annually, the fastest pace since December 2022 and well above the expected 5.3 percent.
The inflation reports reinforced concerns that interest rates, which set the pace for borrowing costs, could remain elevated for longer, putting pressure on technology companies whose valuations depend heavily on future earnings and whose expansion calls for substantial capital.
By contrast, the Dow Jones Industrial Average gained 0.67 percent for the week, closing Friday at 52,000. The S&P 500 fell 1.95 percent to 7,659, while the small-cap Russell 2000 lost 3.05 percent. Both the S&P 500 and Nasdaq finished near their weekly lows.
Inflation, Bond Yields Challenge AI Optimism
The 10-year Treasury yield climbed above 5.30 percent during Wednesday’s trading before retreating toward 5.20 percent.
On Thursday, investors sought the relative safety of government bonds amid concerns about the creditworthiness of AI infrastructure companies, sending the 10-year yield down nearly 13 basis points to 5.05 percent. The 30-year Treasury yield also edged lower, to 5.43 percent.
The swings in bond yields illustrated how sensitive equity valuations have become to inflation expectations and the cost of capital. Higher yields reduce the present value of future corporate earnings and raise the cost of financing capital-intensive projects, leaving little or no “margin of safety,” to use Warren Buffett’s terminology.
Skyler Weinand, chief investment officer of Dallas-based Regan Capital, said the latest CPI report strengthened his view that inflation was proving stubborn and moving in the wrong direction.
“The inflation uptick is likely to lead the Federal Reserve to start a rate-hiking cycle,” Weinand told The Epoch Times. He expects the central bank to pause in October but anticipates rate increases beginning in December and continuing through June 2027.
Elizabeth Renter, who recently joined Life360 as lead economist, said energy costs drove September’s price increases, affecting consumers both directly through gasoline and indirectly through airfares as airlines faced higher jet-fuel expenses.
“Though July and August provided some relief at the pumps, it was modest and short-lived,” she told The Epoch Times, adding that the latest inflation reading increased the likelihood of another Federal Reserve rate hike.
Dennis Follmer, chief investment officer of Montis Financial, said investors should begin treating a 10-year Treasury yield above 5 percent as a potential new normal rather than a temporary anomaly. The Waltham, Massachusetts-based firm manages $1.4 billion in assets.
“For years, the Treasury enjoyed the luxury of having huge rate-insensitive buyers, such as China, Japan, and the Fed, but those buyers are gone now, and Treasuries have to offer competitive returns at a time when they are increasing supply due to the government’s profligate spending, which itself is giving creditors reason to require a higher rate of return,” Follmer told The Epoch Times.
If elevated yields persist, the implications could go beyond technology stocks to small-cap companies and other businesses that depend on external financing.
AI Infrastructure Faces Profitability Test
The pressure on AI stocks was especially pronounced among companies building the infrastructure essential to support the industry’s expansion.
CoreWeave, which operates cloud infrastructure in the United States, fell sharply as investors questioned the returns available from the capital-intensive AI business. According to GuruFocus estimates, CoreWeave has a return on invested capital of negative 0.45 percent, compared with an estimated weighted average cost of capital of 8.97 percent.
That gap suggests the company is not currently earning enough on its invested capital to cover its cost of financing. If this relationship continues as the company expands, growth could destroy rather than create economic value for capital providers.
Nebius Group, which builds full-stack infrastructure for the global AI industry and has similar financial characteristics, also suffered substantial losses. The declines suggest that investors are becoming more selective about AI-related investments, rather than assuming rising demand for computing capacity will automatically translate into attractive returns.
Oracle also fell 8.33 percent on Wednesday as concerns grew about large technology companies’ ability to finance AI projects in a higher-rate environment. CoreWeave dropped 15.46 percent that day.
The issue matters most for companies committing large sums to data centers, computing equipment, and related infrastructure. Such investments require considerable upfront spending, while the timing and magnitude of the resulting cash flows remain uncertain. Rising financing costs can further weaken returns if revenue growth and operating profitability fail to keep pace.
The retreat in AI shares also illustrates the difference between business expansion and value creation. A company can expand sales and investment rapidly without generating superior market returns for capital holders—returns that exceed its cost of capital.
Corporate Profits Under Scrutiny
Investors are also looking to third-quarter earnings for evidence that corporate profitability can support stock valuations amid rising borrowing costs and ongoing inflation.
Clark Bellin, president and chief investment officer of Lincoln, Nebraska-based Bellwether Wealth, said earnings season matters because corporate profits have driven much of this year’s stock-market gains.
“This is one of the most important earnings seasons, since much of the stock market’s gains so far this year have been driven by earnings, and investors want further confirmation that the earnings picture is still intact,” Bellin told The Epoch Times.
He identified three key questions: how companies are deploying AI and profiting from it, whether they can maintain or increase pricing power, and how they are coping with higher borrowing costs.
Results from major banks also provide an early indication of the health of the economy and financial system. Goldman Sachs and Citigroup exceeded expectations for both revenue and earnings, while JPMorgan missed on both.
Wells Fargo beat earnings expectations yet fell short on revenue. Citigroup shares fell 5.60 percent on Tuesday, pushing the Invesco KBW Bank ETF down 1.39 percent.
Brett Kenwell, an investment strategist at eToro, said bank and credit card company results would offer important insights into household finances, especially as inflation continues to outpace wage growth. Meanwhile, technology companies are expected to provide further insight into the durability of the AI investment cycle.
The earnings picture has so far offered mixed signals. Johnson & Johnson shares fell 5.73 percent on Tuesday despite strong earnings, while defensive pharmaceutical stocks helped support the Dow during the broader technology sell-off.
Market Rotation Limits Broader Losses
Money moving out of technology stocks and into other sectors helped cushion the wider market. On Wednesday, the Nasdaq and Russell 2000 fell 1.88 percent and 1.93 percent, respectively, while the S&P 500 declined 1.11 percent. The Dow managed fractional gains as investors rotated toward defensive shares, including Johnson & Johnson and Merck.
The rotation continued Thursday. Although semiconductor shares initially fell sharply after South Korea’s Kospi index dropped 7.57 percent overnight, bargain hunting helped reverse some of the losses.
The Nasdaq ultimately closed slightly higher, supported by gains in Salesforce, ServiceNow, and Microsoft, which rose 4.57 percent, 6.4 percent, and 1.08 percent, respectively.
Lower Treasury yields also supported equities. The Russell 2000 gained 1.24 percent, while the Dow advanced 1.08 percent and the S&P 500 rose 0.33 percent.
The week’s volatility began with oil prices, which climbed as geopolitical tensions renewed concerns about supply disruptions. Brent crude rose more than 1 percent on Monday, Oct. 12, to above $106 a barrel, its highest level in more than two weeks, according to Trading Economics.
Technology shares were already under pressure on Tuesday, when chip manufacturing equipment makers suffered substantial losses. Applied Materials fell 6.69 percent, while Lam Research and KLA each lost about 4 percent, pushing the Philadelphia Semiconductor Index down 1 percent.
The semiconductor weakness followed a 5.46 percent decline in South Korea’s Kospi index. Software stocks and Apple helped limit the Nasdaq’s losses during Tuesday’s session, but the subsequent inflation reports intensified the selling.
The market’s relative strength outside technology indicates investors haven’t changed their asset allocation or shifted away from equities altogether. Instead, they are reassessing which companies can sustain earnings growth and yield superior market returns as capital gets more expensive.
Q4 Outlook Is Divided
Despite the sell-off, Follmer remains optimistic about stocks. He sees two key supports for equities in the fourth quarter: a reaccelerating economy and the prospect of a third consecutive quarter of earnings growth that exceeds already elevated expectations.
“Unless there is some surprise deceleration in earnings, it is very difficult to see how stocks would fail to end the year higher from current levels,” he said.
But he cautioned that the outlook could change if the Federal Reserve enters 2027 increasingly concerned that it has fallen behind the inflation curve.
That risk leaves investors with both a tailwind and a headwind. Strong economic activity and corporate earnings could support stock prices, while continued inflation, higher Treasury yields, and escalating AI infrastructure spending could pressure valuations and tame returns.
For AI investors, the central question is increasingly whether the industry’s expected growth will translate into profits and returns on capital sufficient to justify the money being spent. The week’s losses suggest that, at least for some of the market’s most heavily valued AI companies, investors are demanding clearer answers.
More Stories
Weather System Off North Carolina Could Become Nor’Easter or Tropical Storm: What to Know
By T.J. Muscaro The National Weather Service and its National Hurricane Center are tracking a storm system sitting off the...
Republican Attorney General Candidate New York, Saritha Komatireddy, Lays Out Her Vision
By Juliette Fairley Fresh off a fiery political debate last week, Republican challenger Saritha Komatireddy on Oct. 15 laid out...
Chaos and Violence Grip France as Far-Left Mobs Storm City Halls, Torch Streets
By Etienne Fauchaire PARIS—Stones and fireworks were already flying across Place de la République before Saturday’s demonstration against rising costs...
High Gas Prices Could Be the Key Issue That Swings the Senate
By Jeremy Lott Enough voters are fixated on the price of fuel that it could be the deciding issue in...
Treasury Sanctions Iraqi Bank and Iranian Shadow Networks
By Kimberly Hayek The Treasury Department has sanctioned the Iraq-based International Development Bank for Investment and Finance (IDB) and related...
Trump Seeks to Boost Georgia Voters at Rally With Early Voting Underway
By Troy Mters DALTON, Ga.—President Donald Trump, aboard Marine One, flew directly over hundreds of supporters gathered for his rally...