US Manufacturing Expands for 10th Straight Month Amid High Input Costs

By Bill Pan
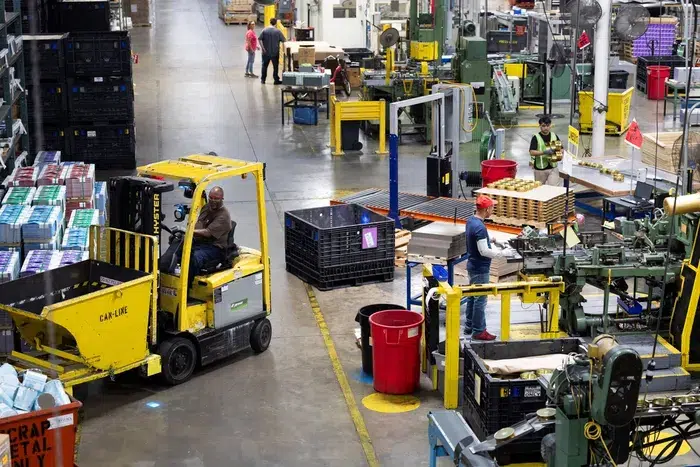
U.S. manufacturing activity strengthened in October as new orders increased, although raw materials became more expensive and took longer to arrive.
The Institute for Supply Management’s Manufacturing Purchasing Managers’ Index, or PMI, rose to 55.5 in October from 54.5 in September, marking the 10th consecutive month of expansion.
The broader U.S. economy expanded for the 24th consecutive month, ISM said on Monday.
The index is based on a monthly survey of manufacturing executives and measures whether business conditions such as orders, production, and employment are improving or weakening.
A reading above 50 generally means an expansion when compared with the previous month, while a reading below 50 points to contraction. The further away from 50, the greater the level of change.
Four of the five components used to calculate October’s headline PMI—new orders, production, supplier deliveries, and inventories—picked up from September, while employment growth slowed slightly.
Production was a particular area of strength. ISM’s Production Index rose 2.3 points to 59.0, its highest level since November 2021.
The New Orders Index edged up to 55.5 from 55.3 and remained in expansion territory for the 10th consecutive month.
Five of the six largest manufacturing industries expanded during October, including machinery, computer and electronic products, transportation equipment, chemicals, and food, beverage, and tobacco products.
The report adds to evidence that the U.S. economy entered the fourth quarter with steady momentum.
The U.S. Department of Commerce said last week that gross domestic product grew at a 3.4 percent annualized rate during the third quarter, accelerating from 2.2 percent in the second quarter.
Consumer spending and business investment were among the contributors to growth.
AI Demand Supports Some Manufacturers
Spending on artificial intelligence (AI) infrastructure has become an increasingly important source of demand for manufacturers of computers, electrical equipment, machinery, and other components used in data centers.
One machinery manufacturer told ISM that an “explosive growth” in demand from semiconductor and defense customers had stretched lead times and pushed prices to levels reminiscent of the COVID-19 era.
A transportation equipment manufacturer, meanwhile, said its customers, as well as its customers’ customers, remained cautious about making large purchases.
The company said the normal fourth-quarter increase in orders, when customers often spend their remaining annual budgets, had not materialized as expected.
Another transportation equipment manufacturer described the trucking industry as experiencing “mixed signals.” Freight demand “appeared softer,” the company said, but elevated diesel prices continued to support trucking companies’ revenue through fuel surcharges.
ISM said only 34 percent of respondents’ comments expressed positive sentiment, while 66 percent were negative.
Among the negative comments, 62 percent cited price volatility, 41 percent mentioned longer lead times, 25 percent referred to tariffs, and 21 percent pointed to the war involving Iran.
Material Costs Remain Elevated
Manufacturers continued to face substantial price pressures, with raw-material prices having increased for 25 consecutive months.
ISM’s Prices Index fell to 75.2 from 77.9 in September. The decline indicates that prices were rising more slowly, but the reading remained well above the 50 baseline.
More than 53 percent of manufacturers reported paying higher prices in October, while just 2.8 percent said prices had fallen.
“Any commodity consumed by AI/data centers is in a crunch, both for supply and pricing,” one manufacturer told ISM. “We keep wondering when the madness will stop.”
A food and beverage producer also reported higher transportation costs stemming from elevated diesel prices and a shortage of truck drivers, on top of increases in raw-material costs.
Supplier deliveries also remained slow in October, with that index edging up to 59.1 from 59.0 in September. A reading above 50 means deliveries are taking longer.
Slower deliveries typically reflect stronger customer demand. But delivery times can also be prolonged by material shortages, transportation bottlenecks, and geopolitical disruptions.
Five of the six largest manufacturing industries reported slower supplier deliveries in October.
The Inventories Index rose to 51.4 from 48.6, indicating that factory inventories have returned to expansion.
Customer inventories, meanwhile, remained at levels ISM described as “too low,” a condition generally considered supportive of future factory production because customers may need to replenish stocks.
Other Survey Shows Expansion
A separate survey from S&P Global also pointed to solid manufacturing activity in October.
Its preliminary U.S. Manufacturing PMI rose to 56.0 from 55.9 in September, reaching its highest level since May 2022.
The S&P survey also highlighted intensifying cost pressures, noting that manufacturers have been increasingly able to pass those higher costs on to customers.
“October consequently saw another leg-up in terms of manufacturers’ selling price inflation to the steepest since September 2022,” Chris Williamson, chief business economist at S&P Global Market Intelligence, said in a statement.
“Such steep growth in factory gate prices will inevitably feed through to consumers in the coming months.”
More Stories
The World Looks Upside Down…But It Isn’t
By Louis Navellier The world seems to have been turned upside down, and we are suddenly all living in “Opposite...
US Oil Prices Fall More Than 7 Percent on Iran Peace Talks
By Andrew Moran Crude oil prices fell sharply to start the trading week on hopes of peace talks with Iran....
Appeals Court Allows Trump Admin Effort Targeting Noncitizen Voting
By Zachary Stieber A federal appeals court on Nov. 3 reinstated a decision that stays a restraining order that had...
America Votes: What to Expect
By Lawrence Wilson Democrats appear poised to win control of the House and possibly the Senate on Nov. 3 as...
One Canadian Confirmed Among 69 Victims of Fatal Spanish Train Crash
By Jennifer Cowen Global Affairs has confirmed one Canadian was killed in last week’s high-speed rail collision in Spain. Sixty-nine...
All of Us Are Dead Season 2: Recent Updates and Cast Members
After letting fans wait for almost 4 years, All of Us Are Dead is getting ready for the continuation of...