Healey blinked on bank tax, but mortgages, savings and pensions will feel it

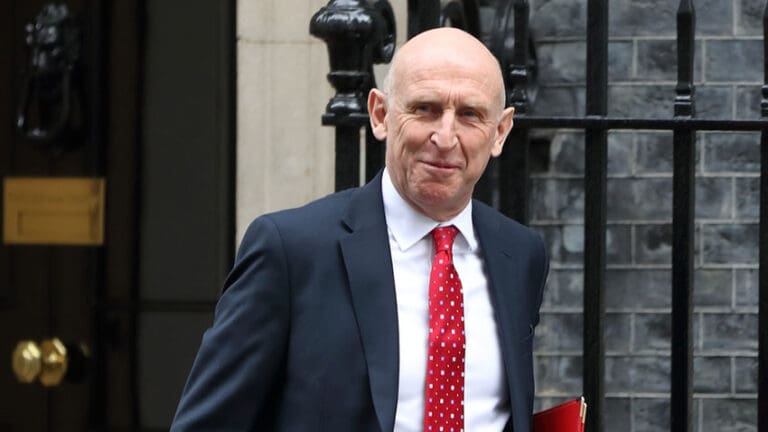
Chancellor John Healey has used his first Budget today to add 3 per cent to the bank surcharge from January, doubling it to 6 per cent for 15 months. Banks feared an 8 per cent hammer blow. They didn’t get one.
Credit where it’s due, the Chancellor blinked. He was under enormous pressure to go to 8 per cent and leave it there for good, and he didn’t.
The sector will take this one on the chin.
But a smaller tax is still a tax, and banks don’t pay it out of thin air. Every pound the Treasury takes is a pound that can’t be lent to a young couple buying their first home or a small firm trying to expand.
What the rise means in numbers
The increase lifts the combined tax rate on UK banking profits above £100m to 31 per cent, with a separate levy on balance sheets charged on top. It lands on an industry whose tax bill already climbed 8.5 per cent to £39.1bn last year.
I understand why the Treasury went looking. Economists had said Healey would need to find about £10bn in tax rises or spending cuts in this Budget, and banks were always going to be near the top of the list.
Supporters of the move point to the roughly £15bn the biggest lenders made in the first half of 2026, much of it from the wide gap between what they charge borrowers and what they pay savers.
Those profits ride the interest rate cycle. When rates fall, margins will follow.
A tax justified by one strong year still has to be paid in the weaker ones, and that’s when it starts to bite on lending.
Who pays first
Bank shares spent much of October sliding as talk of a raid grew, then bounced on reports the rise would be smaller and temporary. Investors, it seems, had feared something much worse.
But the people who feel it first won’t be in the City.
It shows up quietly, in a remortgage quote that’s dearer than it might have been, or a savings rate that never quite catches up. It shows up in the pension funds and ISAs that own bank shares and depend on their dividends.
Nobody gets a letter saying the Budget did it.
The Chancellor says he celebrates and is grateful for the role banks play in the economy. You can’t thank the banks for holding the economy together and reach into their pockets in the same speech. Gratitude doesn’t normally arrive with a bigger tax bill.
The real test comes in 2028
That is why the promised end date is now crucial.
The test for this Chancellor arrives in spring 2028, when the surcharge is meant to fall away. If it goes on time, Britain tells every bank deciding where to grow that this is a country which keeps its word. If it gets extended, nobody will believe the next promise.
Global banks don’t need much excuse to book business elsewhere.
Financial centres from the Gulf to Asia are chasing the people and capital London spent decades attracting, and they’ll happily hold up today as proof Britain changes the rules whenever money gets tight.
The timing could hardly be worse for Britain’s ambitions in finance, and it sits awkwardly in a Budget that also carries an AI investment package meant to show the UK is serious about the technology.
The industry is heading into a period of enormous change, with AI reshaping lending and tokenisation set to transform how assets are bought and sold. The countries that lead it will be those where banks feel confident enough to invest heavily now.
A surcharge with a firm end date might be survivable. One that keeps coming back would leave London watching from the sidelines.
Healey spared the City the worst. Households and businesses won’t be so lucky.
They’ll be paying for this through their mortgages, their savings, and their pensions long after the relief in the banks has faded.
More Stories
Healey cuts electricity bills by a quarter for 10,000 industrial firms
Chancellor John Healey today announced a British Industrial Competitiveness Scheme that will take 25 per cent off electricity bills for...
Healey raises minimum and living wages by 3.9 per cent
Chancellor John Healey today increased both the National Minimum Wage and the National Living Wage by 3.9 per cent, a...
Healey extends energy VAT cut and raises bank surcharge in Budget
Chancellor John Healey today extended the cut to VAT on household electricity bills to July and announced a temporary rise...
Healey lifts small business rate relief threshold to £18,000
Chancellor John Healey today raised the threshold for small business rate relief for retail, hospitality and leisure businesses from £12,000...
Healey unveils 10 per cent Founders Relief and halves BADR limit
Chancellor John Healey today announced a new capital gains tax relief for business founders, charging 10 per cent on lifetime...
Sundas “Sunny” Naqvi on the Discipline Behind a Creative Life
Raised in southern England, Naqvi began singing through school choirs and local community performances. Those early experiences gave her a...